We could see a sharp trading rally in Shriram Transport if the health scare abates or the risk on trade makes a comeback. So, this is a stock for the risk taker and best avoided by a conservative investor
Highlights
-
Stock has underperformed the index year to date
- Growth in slow lane
- Moratorium picture has
improved
- Higher provision for Covid
mars profit and provision could remain high
- Asset quality improves in
the quarter but future looks uncertain
- Diversified funding a
positive, rights issue provided further capital buffer
- Valuation attractive, but inherent
volatility makes it a stock for risk takers
Shriram Transport has been a big under- performer in the
market despite the stock rallying from its nadir hit in March. The stock has
risen 41 per cent from its March lows as against 48 per cent for the Nifty
index. The insipid show by Shriram Transport is a bit surprising because the
rural sector, which is a key market for the company, is looking up on the back
of a good monsoon and lockdown restrictions are increasingly being eased.
Moreover, the recent rights issue has given enough capital cushion to the
company to face the probable rainy day. Then what ails this leader of second
hand vehicle financing, despite the segment remaining relatively insulated
compared to first hand CVs?
We see growth to be a
challenge even beyond Covid
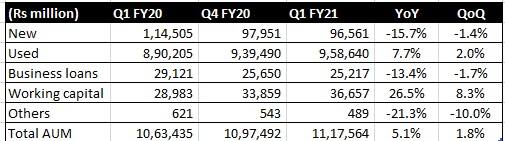
Growth was quite tepid in the last reported quarter. Used
vehicles and working capital drove the overall year-on-year (YoY) growth in
assets under management (AUM) to 5 per cent. Disbursements declined by close to
92 per cent YoY.
Source: Company
However, this is not a one-time decline as the pace of growth
had been decelerating for the last several quarters. While the rural segment is
doing better (40 per cent of AUM comes from rural), the overall sluggishness in
the economy would be a key impediment to growing a relatively large book unless
Shriram dilutes its underwriting standards.
Asset quality – good but not out of the
woods yet
In the last reported quarter, asset quality was stable with
gross and net stage 3 assets at 7.98 per cent and 5.06 per cent of total assets
respectively as against 8.36 per cent and 5.62 per cent in the previous
quarter. In fact, collection that had fallen during the lockdown — from 84 per
cent in March to 23 per cent in April and rose to 52 per cent in May — recovered
in July and stood at 73 per cent in terms of borrowers and 53 per cent in terms
of value. While this means that the moratorium book has reduced from close to
70 per cent by value in May, it remains large enough to warrant caution.
Credit cost to remain a drag on
profit
The historic credit cost of Shriram Transport has been around 2
per cent of assets. In the quarter gone by, the reported profit was pulled down
by a Covid provision of Rs 956 crore. The total Covid provision is close to Rs
1,866 crore, which is a little over 3 per cent of the moratorium book. We have
factored in a very high level of credit cost in FY21e.
Margins under pressure
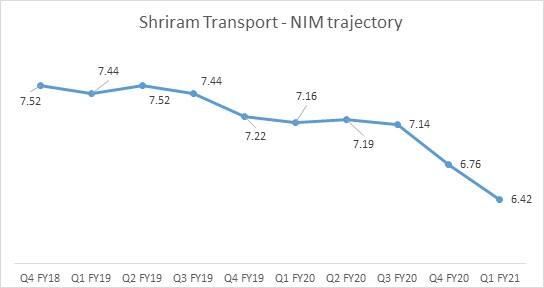
The company has seen a steady decline in its margins thanks to
more than adequate liquidity and competitive rates on yield on advances. The
buffer liquidity and SLR investments as of August was Rs 9,687 crore and Rs
1,822 crore respectively. The company has also raised Rs 1500 crore by way of a
rights issue that should shore up its capital adequacy ratio, which is already
comfortable at 21.9 per cent.
Source: Company
What are the redeeming features?
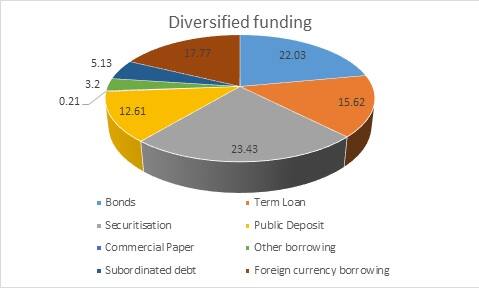
Shriram Transport Finance is a large deposit taking NBFC and a
likely survivor post the mayhem that is sweeping the NBFC universe. It has a
diversified funding base and could continue to garner funds from different
sources, including foreign borrowings and banks. It may be noted here that
on-lending to NBFCs is now considered a part of bank’s priority sector
exposure. So we do not foresee a structural liquidity challenge.
Source: Company
While short-term asset quality hiccup cannot be ruled out, we
draw comfort from the fact that for 70 per cent of the borrowers, the vehicles
are back on the road. Moreover, with a distinctive preference for used vehicles
by the rural population, the increase in farm income due to a good harvest and
a normal monsoon should augur well for demand as well as asset quality. Should
the much-awaited scrappage policy get implemented, it could breathe new life to
the commercial vehicle segment.
However, for Shriram, in addition to the growth and asset
quality worries, there is the looming risk of the merger with group companies.
Such a merger will dilute the unique characteristics of its expertise in the
used vehicle market. This isn’t imminent though owing to the ongoing pandemic.
Earnings could remain volatile as nearly half of the loan by value goes to
heavy commercial vehicles where economic slowdown could adversely impact
freight rates and cash flow of borrowers.

Source: Company, Moneycontrol Research
We have assumed a subdued loan growth in FY21 and a much higher
credit cost than what has been indicated by the management, thereby resulting
in a substantial near-term earnings decline. However, a recovery is likely in
FY22e. While valuation looks particularly attractive from the FY22e
perspective, the stock might remain volatile. We could see a sharp trading
rally if the health scare abates or if the risk on trade makes a comeback. So
this is a stock for the risk taker best avoided by a conservative investor.
Comments
Post a Comment